Seven states produced approximately 95% of the 40 million metric tons of salt mined in the US in 2025, according to the US Geological Survey (USGS). Road-maintenance buyers, however, are spread across thousands of counties and municipalities far from the producing regions. Ports, rail, and trucking increasingly decide how much salt a producer can sell, often more than the size of its reserves.
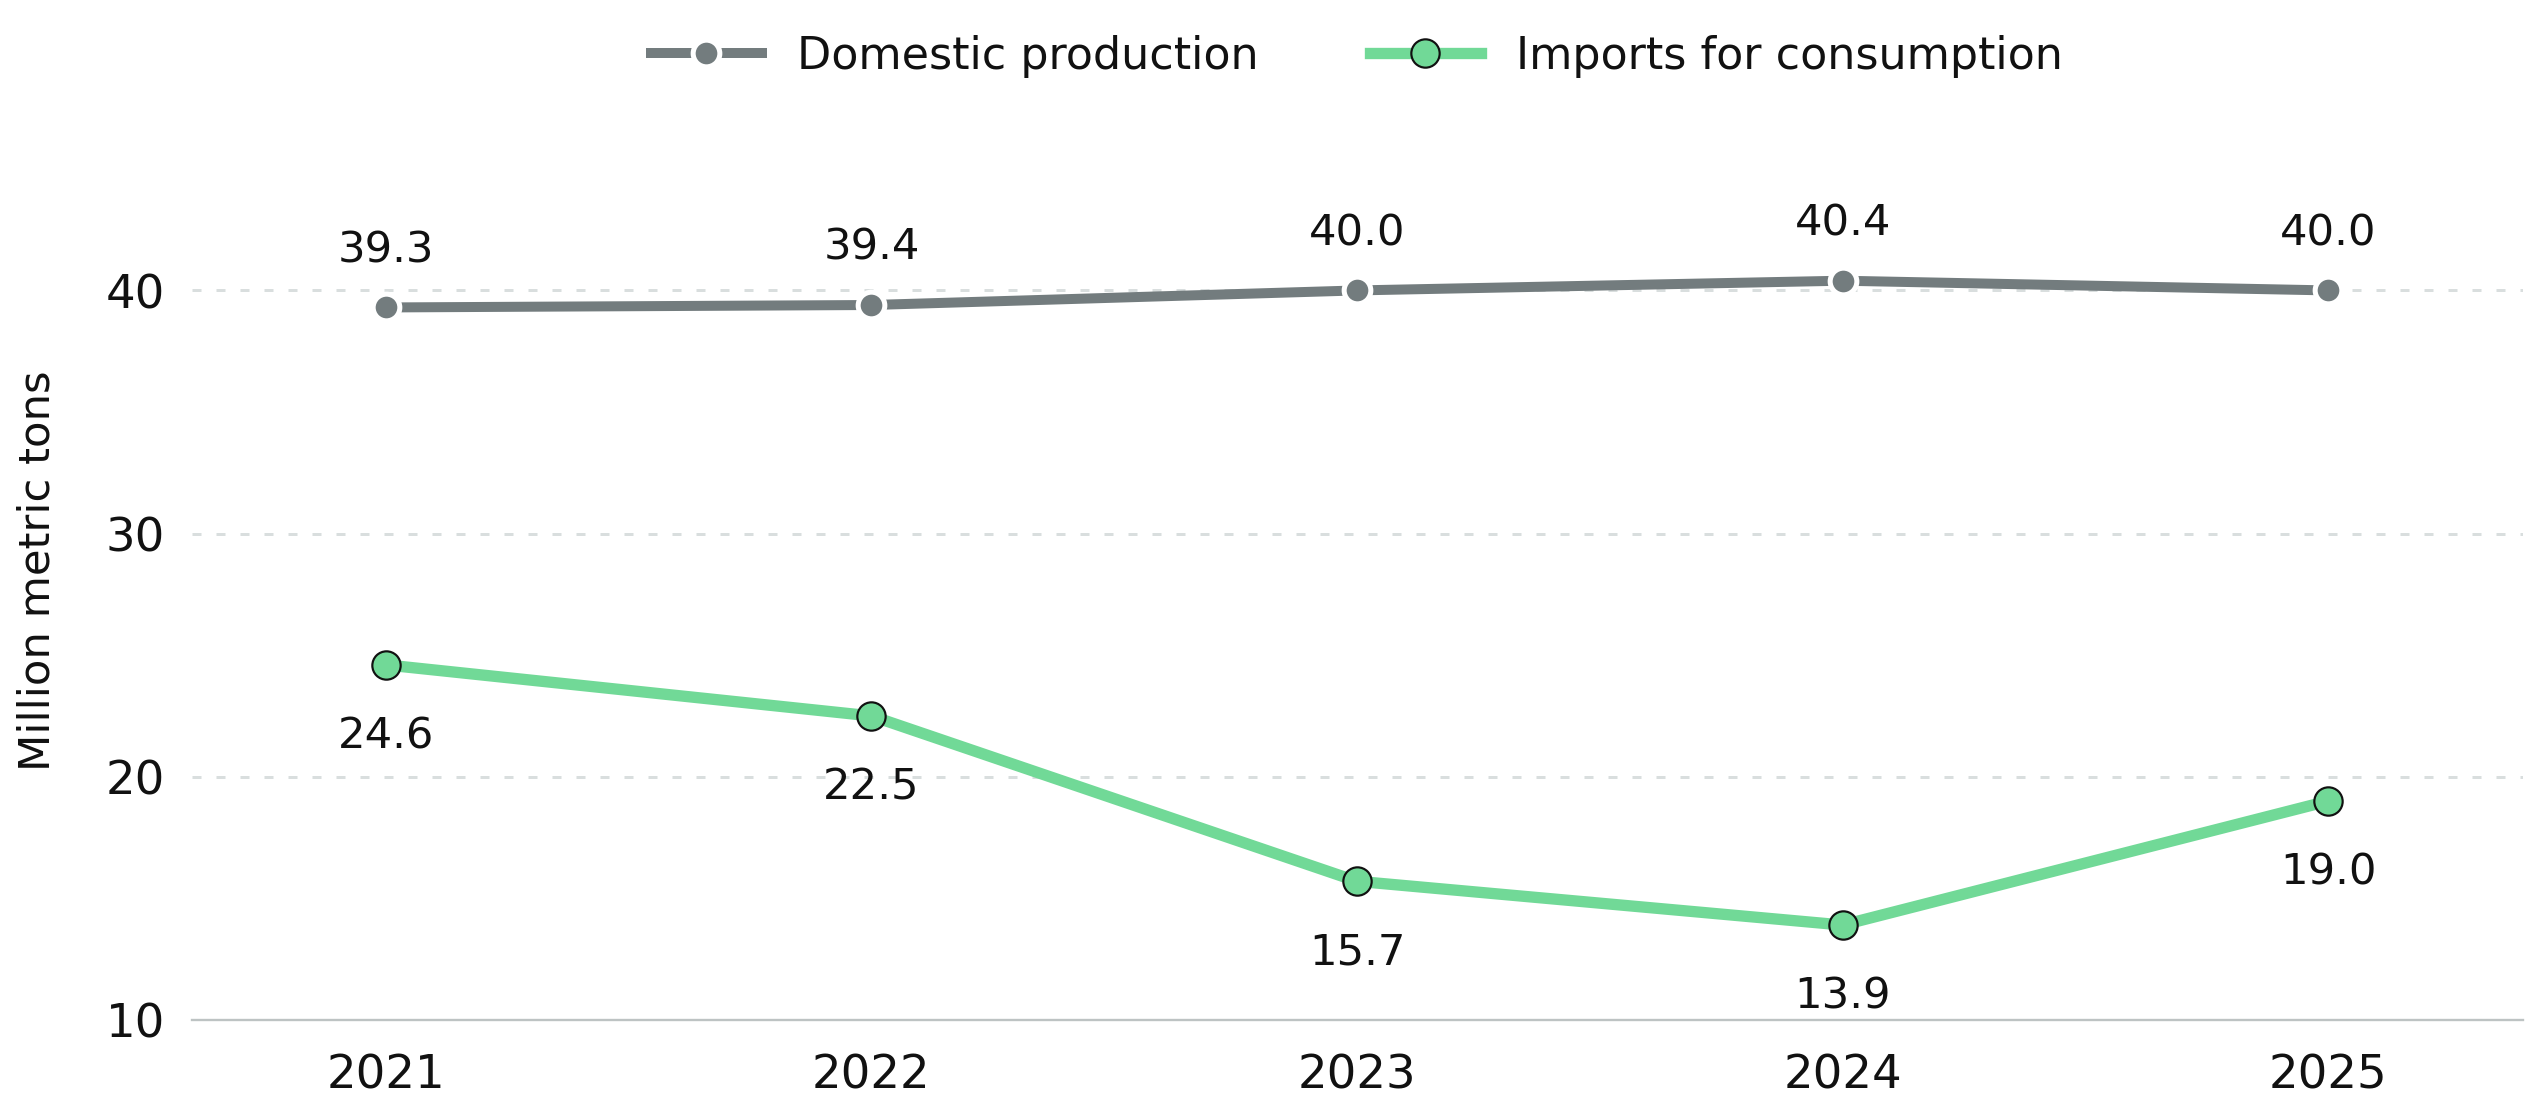
Concentrated US Salt Output Makes Transport Routes Decide Who Wins Inland Contracts
Highway de-icing accounted for 37% of US salt consumption, making low-cost freight the entry point to road-maintenance demand. The Iowa Department of Transportation buys approximately 200,000 tons of rock salt a year for 113 delivery locations. Kansas salt arrives by rail and truck, while Louisiana supply moves by Mississippi River barge before final trucking, letting distant producers compete for inland demand.
Marine Terminals Let Salt Suppliers Reach Big Cities Far From the Mine
The Port of Toronto handled 751,353 metric tons of road salt in 2025, with rail and highway links carrying bulk shipments on to inland customers. In February 2025, Erie County, New York, secured 1,000 tons of Ontario rock salt per day through the Port of Buffalo, targeting 5,000 tons the following week for county highway facilities and surrounding municipalities.
Delivery-Inclusive Prices More Than Double Across Areas, Rewarding Low-Cost Distribution
Massachusetts' 2026-27 road-salt schedule lists delivery-inclusive contract ceilings of US$68.55 per ton in Area 5C, US$73.25 in Area 5D, and US$181.70 in Area 5E for the same supplier. Transport costs therefore shape which markets can be served profitably. Marine terminals, rail, and final-mile trucking expand the number of markets where producer netbacks, or revenue left after distribution costs, stay competitive.
State Minimum-Purchase Contracts Reward Salt Suppliers Who Can Guarantee Delivery Capacity
New York State's April 2026 procurement bulletin requires most participating buyers to purchase at least 60% of their stated road-salt requirements, while suppliers must guarantee deliveries up to 130%. Pennsylvania's 2025-26 contract sets the same 60% floor with supplier coverage up to 140%. For pre-production projects, such commitments offer more predictable sales volumes than regional demand estimates, provided planned logistics can meet delivery obligations.
Coastal Port Access Shortens Shipping Times to Major East Coast Markets
Port proximity and inland rail links add the most value when planned production can serve major customers without long transport routes.
Atlas Salt ($SALT), advancing Newfoundland's Great Atlantic Salt Project, plans a conveyor to Turf Point Deep Water Port and estimates shipping times under 3 days to Boston, against more than 14 days from Egypt or Chile. A non-binding Canadian National Railway agreement explores inland distribution.
Nolan Peterson, Chief Executive Officer of Atlas Salt, explains how the company maps demand:
"We have modeled the entire North American market, including every selling jurisdiction, county, city, and municipality, to determine how much salt they buy and how it can reach them from mines and suppliers around the world that could realistically serve them."
Market Reach Sets How Much Salt a Mine Sells
Iowa's rail and barge routes and Toronto's marine volumes show concentrated production reaching dispersed customers, separating the salt a mine can produce from the volume it can competitively sell. For development-stage projects, port, rail, and inland delivery connections expand addressable markets without larger reserves. Their value depends on generating enough sales at competitive delivery costs to justify the infrastructure spend.
Salt Value Rests on Turning Low Mining Costs Into Delivered Volume
Concentrated production leaves dispersed road-salt buyers dependent on freight. Projects pairing competitive mining costs with financeable port and rail access, backed by minimum-purchase government contracts, can convert reserves into dependable sales. Market recognition of mine value follows once transport links and supply contracts move from non-binding plans to signed, funded commitments.
Read more: US Salt Production Concentration Puts Distribution Ahead of Mine Size
Disclosure: The article features Atlas Salt as a company example. The company had no influence over the topic, thesis, or conclusions of the article, and exercised no editorial control over its content.
