Worldwide semiconductor sales reached US$159.7 billion in August 2026, up 144.3% year over year, with cumulative sales through August above US$1 trillion. The Silver Institute still forecasts industrial silver demand falling 3% to 639.6 million ounces this year, with photovoltaic demand down 19%. Silver's largest industrial buyer is thrifting faster than its newest one is scaling.
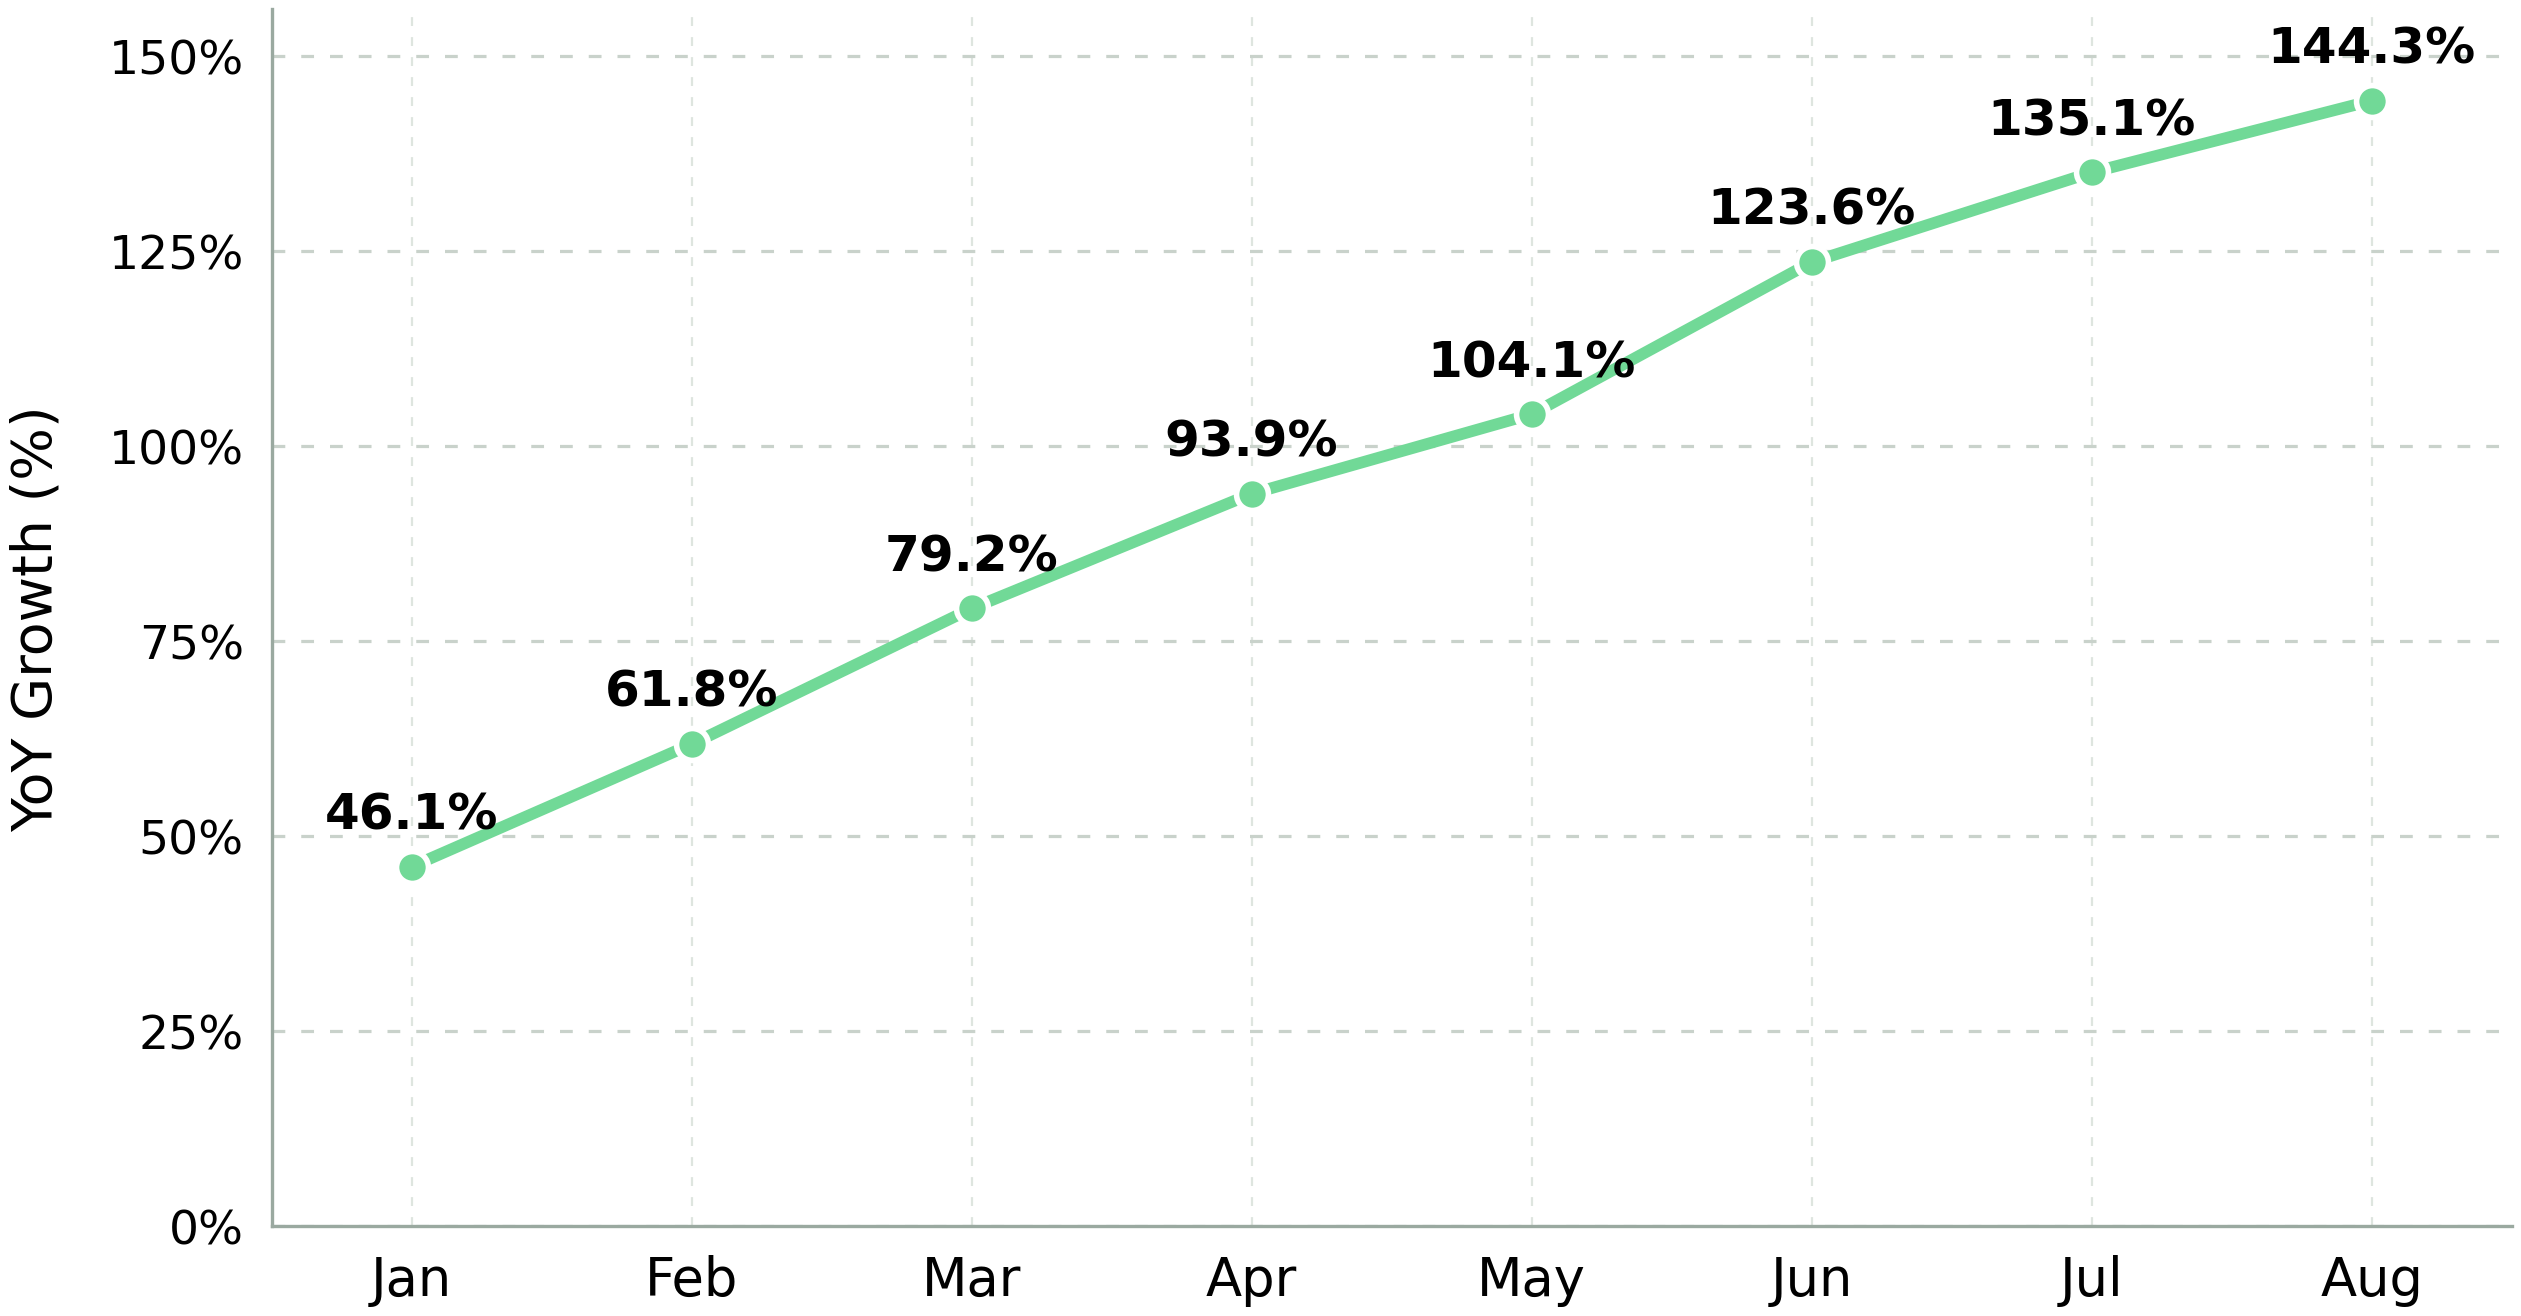
Chip Equipment Spending Builds a Second Industrial Buyer for Silver
SEMI forecasts global spending on 300-millimeter chipmaking equipment to rise 31% to US$149 billion in 2026 and US$227 billion by 2029, with construction starting on 20 new fabrication facilities or production lines this year. That capacity installs on multi-year schedules, so the silver it carries arrives as a rising baseline rather than a single demand step.
Packaging Adoption Turns Chip Growth Into Silver Demand
Silver's electrical and thermal conductivity places it in semiconductor packaging, connectors, power modules and thermal-management materials. The USGS put electrical and electronics applications at 25% of US silver consumption in 2025, against 15% for photovoltaics. TANAKA Precious Metal Technologies began a three-year partnership with TNO on October 1, 2026 to develop silver- and copper-based chip-bonding pastes, the commercial step that turns packaging growth into ounces consumed.
Data Centers Become a Measurable Share of Electronics Silver Demand
The IEA projects global data-center electricity consumption to nearly double from 485 terawatt-hours in 2025 to roughly 950 terawatt-hours by 2030, with technology-sector capital expenditure above US$400 billion in 2025 and potentially 75% higher this year. The Silver Institute expects data centers to account for more than 10% of electrical and electronics silver demand in 2027.
Photovoltaic Thrifting Removes More Ounces Than AI Adds This Year
Photovoltaic silver demand is forecast to fall 19%, from 186.6 million ounces in 2025 to 151.0 million ounces, as cell makers cut silver loadings and substitute materials. Total electrical and electronics demand is forecast 6% lower at 422.9 million ounces. Near-term thrifting outweighs near-term gains from AI infrastructure, which makes diversification a 2027-and-later argument rather than a 2026 one.
Producer Output Decides Whether Electronics Demand Finds Metal to Buy
Rising electronics demand only converts if operating mines deliver, and higher processing capacity, improved recoveries and efficient mining operations can increase saleable silver production. Americas Gold and Silver ($USA) reported record third-quarter output of 800,458 silver ounces across Galena and Cosalá and held full-year guidance of 3.2 million to 3.6 million ounces, while Mexican operations support future silver growth.
Funded Development Sets When New Silver Can Reach the Market
The semiconductor industry's multi-year expansion brings future silver supply into focus, where reserves, completed feasibility work and available funding determine timing. Vizsla Silver ($VZLA) holds US$411 million in cash and short-term investments against US$238.7 million of initial capital at Pánuco, where its November 2025 feasibility study models 17.4 million silver-equivalent ounces annually over 9.4 years from the second half of 2028.
Drilling Results Determine What Supply Exists After the Funded Pipeline
Exploration sets what sits behind the projects already financed. GR Silver Mining ($GRSL) confirmed mineralization extending at least 300 meters beyond the existing resource boundary at San Marcial in September 2026, with a 20,000-meter program steering drilling ahead of an updated resource estimate and PEA in the first half of 2027.
2027 Shows How Far Silver’s Demand Shift Can Run
Industrial silver demand falls this year even as its newest buyer scales, so 2026 weakness in the demand data is a mix shift rather than a structural break. Investors should weight exposure toward producers delivering ounces now and developers already funded through construction. The re-rating arrives when 2027 electronics volumes replace lost photovoltaic ounces, with first-half 2027 data the nearest test.
Read more: 144% Chip Sales Surge Supports Silver's Long-Term Demand
Disclosure: This article features Americas Gold and Silver, Vizsla Silver, and GR Silver Mining as company examples. None of the companies influenced the topic, thesis, or conclusions of this article, and none exercised editorial control over its content.
